Home / Business and Economy / Ramco Cements: Hold for Now Amidst Valuation Concerns
Ramco Cements: Hold for Now Amidst Valuation Concerns
10 May
Summary
- Ramco Cements faces margin pressure despite revenue growth plans.
- Capacity expansion is underway, but southern market overcapacity persists.
- Stock valuation is considered rich, prompting a 'hold' recommendation.
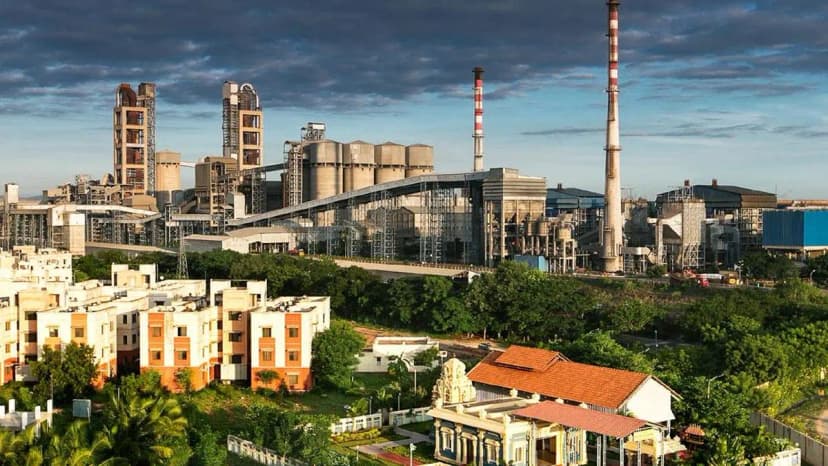
Ramco Cements is undergoing a significant capacity expansion, aiming to increase its installed capacity from 24.4 mtpa to 31 mtpa by FY28. This includes debottlenecking existing plants and a new brownfield expansion in Andhra Pradesh, expected by FY27-end. Despite this growth driver, the company faces margin pressures stemming from rising input costs, such as coking coal, amplified by increased shipping costs due to geopolitical factors.
The southern market, where Ramco Cements holds a substantial revenue share, is experiencing cement overcapacity, limiting price increases. While revenue is projected to grow 12-13% annually through FY28, driven by capacity additions, profit margins are under scrutiny. Recent financial performance shows a 5% year-on-year revenue growth in 9MFY26, with a substantial profit increase attributed to improved realisations and reduced power costs.
The company's stock is currently trading at a premium valuation, prompting a 'hold' recommendation from analysts, who suggest avoiding fresh investments. This cautious stance is due to a combination of potential margin contractions and rich valuations, especially when compared to industry peers. Ramco Cements is also diversifying into construction chemicals, which showed strong growth in Q3FY26.


