Home / Business and Economy / Rupee Fall: Gold Loans Gain, Borrowers Squeeze
Rupee Fall: Gold Loans Gain, Borrowers Squeeze
18 Nov
Summary
- A weaker rupee increases domestic gold prices, strengthening collateral.
- Depreciating currency strains borrower cash flows and repayment ability.
- Lenders balance rising security values against hidden credit risks.
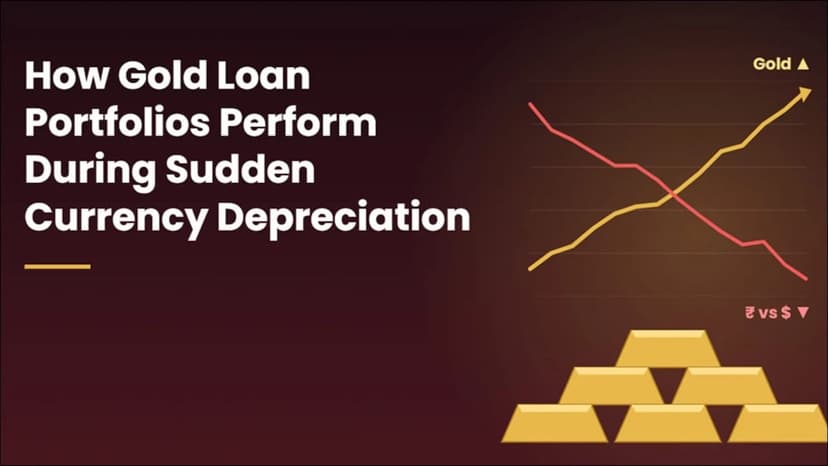
A depreciating rupee can paradoxically strengthen gold loan collateral by increasing domestic gold prices. This currency effect enhances the loan-to-value ratio for lenders, potentially improving recovery prospects in case of default. However, the same rupee weakness elevates imported inflation, impacting essential costs like fuel and machinery.
This surge in expenses strains household budgets and small business margins, increasing repayment pressure on borrowers. Lenders face a complex scenario where collateral appears more robust, yet borrower repayment capacity diminishes. The performance of gold loan portfolios during currency depreciation hinges on which factor exerts greater influence.
New borrowing demand may rise as small traders seek additional working capital and families receiving remittances benefit from favorable exchange rates. Higher gold prices can also increase the indicative loan amount against the same net weight of gold, subject to regulatory limits.
Lenders are advised to monitor various signals, including application volumes, ticket sizes, and renewal trends, as these can indicate underlying liquidity stress. A growing portfolio does not automatically equate to a stronger one, as loan purpose and repayment capacity remain critical.
Effective portfolio management during currency shocks involves tracking missed installments, loan maturities, and borrower segments affected by inflation. The Reserve Bank of India's framework, effective by April 1, 2026, mandates maintaining loan-to-value ratios throughout the loan tenure using prescribed reference prices for actual purity.
Ultimately, assessing portfolio performance requires more than just collateral prices. Lenders must analyze borrower cash flow, repayment behavior, funding costs, and the sustainability of gold price movements. Sound risk management necessitates recognizing both the apparent strength of security and the increasing vulnerability of customers.


